Back to Blog
Fintech & PaymentsFintech and payment
Uganda’s Cash Demand Persists Even as Digital Channels Accelerate
Emmanuel Clifford Gyetuah·October 17, 2026·4 min
Fintech & Payments
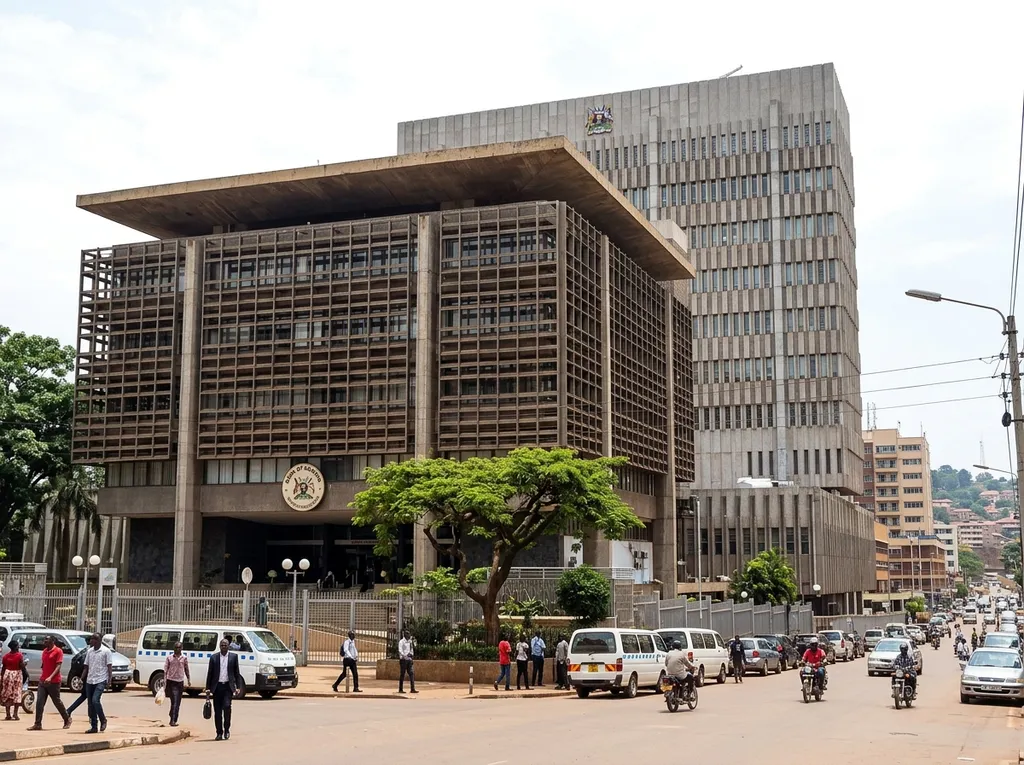
Uganda’s financial ecosystem is experiencing a dynamic structural shift characterized by the rapid expansion of digital payment mechanisms alongside a steady, persistent demand for physical banknotes. According to official data from the Bank of Uganda (BOU) , the total currency in circulation expanded by approximately 12% in the financial year ended June 2026, climbing to roughly Shs10 trillion ($2.45 billion). This continued reliance on paper currency exists alongside remarkable growth in electronic financial channels, creating a compelling case study for central bankers, fintech innovators, and policy strategists across Sub-Saharan Africa.
Between June 2021 and June 2025, central bank statistical records indicate that physical currency in circulation grew at an average annual rate of 10.4%. By comparison, electronic-money transaction values expanded at a compound annual rate of 30.3% over the exact same period. This widening growth gap underlines how rapidly digital channels are taking over higher-frequency, high-value transfers, while physical cash retains a deeply entrenched operational role in local retail markets, informal trade, and rural communities.
Comparative Trajectory: Cash vs. Electronic Money
A closer examination of year-on-year movement reveals a sustained divergence between cash expansion and electronic payment adoption. Electronic-money transaction values demonstrated robust momentum in successive financial years, posting annual growth rates of 37.6% (FY2021/22), 23.7% (FY2022/23), 31.5% (FY2023/24), and 28.6% (FY2024/25). Conversely, cash growth remained constrained in single- to low-double-digit territory over matching periods, registering 13.6%, 7.0%, 12.0%, and 9.3% respectively.
By the calendar year ending December 2025, total electronic-money transactions soared to Shs366 trillion ($89.57 billion), reflecting a 28% increase year-over-year. Concurrently, overall transaction volume reached 9.1 billion, representing a 17.3% surge. Detailed historical trends and macroeconomic frameworks are routinely published in the Bank of Uganda Annual Reports , providing deeper operational context for these figures.
Drivers of Dual-Economy Dynamics
Understanding why physical currency persists alongside rapid digital acceleration requires looking at structural, socio-economic, and technical drivers across the country:
The Informal Sector & Micro-Commerce
A fundamental portion of Uganda's economic activity takes place within informal markets, agricultural transport chains, and localized neighborhood vendor networks. For smallholder farmers, market vendors, and informal transport operators (such as boda-boda drivers), cash offers immediate settlement without transaction fees, network downtime risks, or digital literacy barriers.
Mobile Money Interoperability & Ecosystem Costs
While peer-to-peer (P2P) mobile money transfers are ubiquitous, merchant acceptance fees, cashing-out charges, and government taxes on mobile transfers can still incentivize users to convert digital balances into paper cash for everyday household expenses.
Structural Reliability & Access Infrastructure
In peri-urban and rural areas, mobile network coverage and agent liquidity fluctuate. Physical cash provides absolute transaction certainty, functioning as a necessary safeguard against intermittent connectivity or agent liquidity shortfalls.
Policy Initiatives & Regulatory Reforms
To streamline payment systems, curb cash-handling costs, and broaden formal financial inclusion, Ugandan policymakers are implementing several cornerstone reforms under national strategy agendas managed by the Ministry of Finance, Planning and Economic Development :
National Payment Switch (NPS)
The central bank is driving the implementation of the National Payment Switch to unify fragmented settlement rails. By establishing direct interoperability across commercial banks, mobile network operators (MNOs), and emerging fintech platforms, the NPS aims to dramatically drop transaction fees, eliminate intermediary friction, and accelerate merchant payment adoption.
Second National E-Payments Strategy (2026–2031)
Building on previous digital financial milestones, the upcoming National E-Payments Strategy prioritizes public digital infrastructure, cross-border payment integration within the East African Community (EAC), consumer protection enhancements, and financial literacy campaigns designed to reduce overall cash dependence.
Restrictions on Over-the-Counter Cash Withdrawals
Starting January 2027, the central bank plans to enact structured limits on large over-the-counter (OTC) cash withdrawals at commercial banking halls . This intervention directly encourages corporate and institutional entities to adopt digital clearing houses, real-time gross settlement (RTGS) systems, and corporate e-banking tools.
Strategic Recommendations for Africa Digital Forum Stakeholders
To capitalize on growing transaction volumes while addressing persistent cash usage, ecosystem stakeholders must align around targeted action items:
Expand Low-Cost Merchant Acceptance: Digital payment aggregators and fintechs should deploy interoperable QR code systems and low-fee point-of-sale solutions tailored specifically for micro, small, and medium enterprises (MSMEs).
Enhance Offline Digital Payment Protocols: Technology developers should invest in offline transaction capabilities (via secure hardware or localized ledger technology) to ensure seamless payment execution in low-connectivity areas.
Align Fiscal & Regulatory Policies: Policymakers should carefully balance revenue generation with digital adoption incentives, ensuring transaction taxes do not inadvertently push consumers back into cash-based alternatives.
Uganda’s financial development highlights a broader trend across emerging markets: digital channels can experience exponential growth without instantly liquidating demand for physical currency. As the Bank of Uganda rolls out key structural reforms—including the National Payment Switch and new payment strategies—the transition toward a truly cashless economy will depend on building affordable, inclusive, and highly resilient digital payment infrastructure.
EC
Emmanuel Clifford Gyetuah
Emmanuel Clifford Gyetuah is a versatile leader who specializes in transforming complex financial metrics into actionable strategic insights. Currently, he is the Organizing Director for the Africa Digital Forum, Director at the Media and Digital Institute, and Senior Finance Manager at Bolingo Consult.