Back to Blog
Fintech & PaymentsFintech and payment
Africa’s Digital Transformation Will Be Won at the Last Mile
Ama Dzigbodi Agbodra ·October 20, 2026·8 min
Fintech & Payments
Africa’s digital transformation is often discussed in terms of technological breakthroughs, expanding mobile connectivity, artificial intelligence, fintech innovation and the rapid growth of digital platforms. These developments are important. Across the continent, digital technologies are changing how people communicate, conduct business, access financial services and participate in the economy.
Yet an important question remains: how much value do these innovations create in the everyday lives of the people and businesses they are designed to serve?
The real measure of Africa’s digital progress is not simply how many digital products are launched, how many accounts are registered or how many businesses acquire new technology. It is whether these solutions are accessible, reliable, relevant and capable of delivering meaningful economic value.
Having worked in financial services implementation and fintech product operations, I have come to appreciate an important distinction: introducing technology is one achievement; making it work consistently in the real world is another. The difference between the two is where much of the next phase of Africa’s digital transformation will be determined.
The Last Mile Is Where Digital Ambitions Meet Reality
In digital transformation, the last mile refers to the point at which technology reaches its intended users and becomes part of their everyday activities. It is where a digital strategy encounters the realities of a merchant's business, a customer's expectations, an institution's processes and the infrastructure available to support the service.
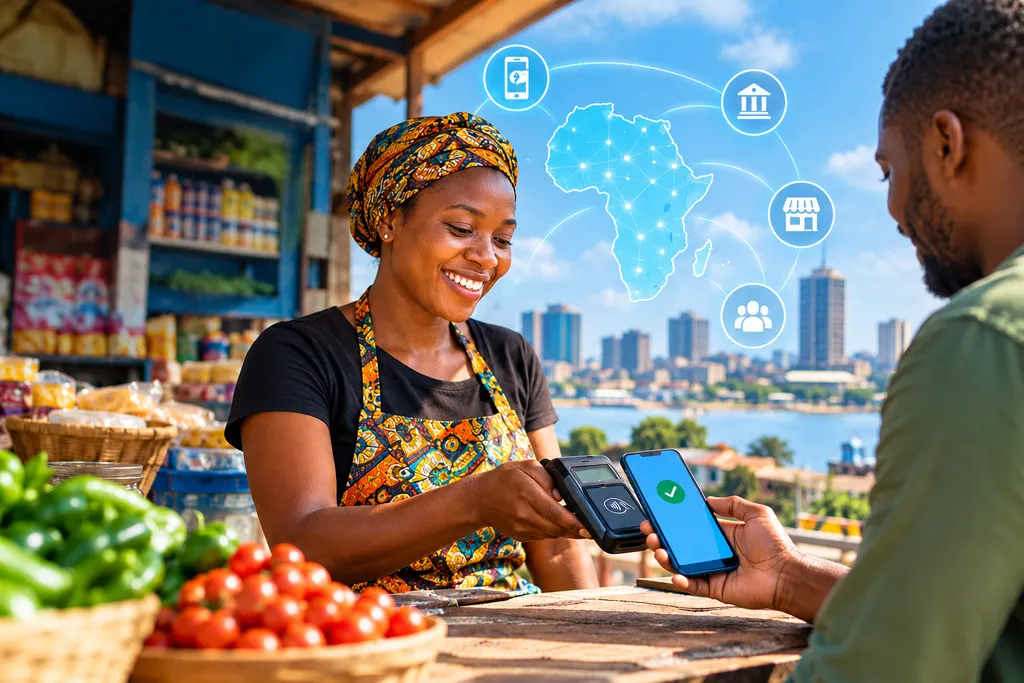
Consider a small business adopting a point-of-sale (POS) terminal to accept electronic payments. The technology may be available, the software developed and the necessary partnerships established. However, the real value of that investment depends on what happens after deployment.
Can the merchant complete transactions reliably? Are payments processed and reconciled correctly? Is support available when something goes wrong? Does the merchant understand how to use the service? Does accepting digital payments make business operations easier?
If these questions remain unanswered, the presence of technology alone does not guarantee transformation.
The same principle applies to digital banking, mobile money, e-commerce, agricultural technology and public services. A platform can be technically sophisticated and still fall short if it does not address the practical needs of its users.
The International Telecommunication Union's Facts and Figures 2024 estimated that only 38% of Africa's population used the internet that year, compared with a global average of 68%. The figures illustrate the scale of the connectivity challenge; even as digital services continue to expand. ITU, Facts and Figures 2024 .
The implication is clear: digital transformation must account for the different economic, infrastructural and social conditions in which people access and use technology.
Digital Payments: A Practical Lesson in Transformation
The evolution of mobile money and electronic payments demonstrates both the potential of digital innovation and the importance of effective implementation.
According to the GSMA's State of the Industry Report on Mobile Money 2025, customers paid more than US$100 billion to merchants through mobile money in 2024, with Sub-Saharan Africa accounting for approximately two-thirds of that value. These figures demonstrate how digital payments are becoming increasingly relevant to commercial activity, beyond person-to-person transfers. GSMA, State of the Industry Report on Mobile Money 2025 .
However, the growth of digital payments also highlights an important consideration: payment ecosystems involve more than the customer-facing technology.
Behind a successful transaction are interconnected systems, financial institutions, technology providers, operational processes and support teams. Each component must function effectively for the user to experience a service that feels seamless.
From a product operations perspective, the work does not end when a solution goes live. It continues through transaction monitoring, issue resolution, coordination between stakeholders, testing of changes and the identification of recurring problems.
A transaction failure, for example, is not merely a technical incident. For a merchant, it can mean a delayed sale, an unhappy customer or uncertainty about whether funds have been received. When such incidents occur repeatedly, confidence in the service may decline.
This is why reliability, customer support and operational readiness should be treated as essential elements of product design rather than activities to address after launch.
Digital transformation succeeds when the technology and the processes supporting it are designed together.
Adoption Is Not the Same as Impact
Another challenge is how digital transformation is measured.
Organizations naturally track indicators such as registrations, downloads, devices deployed and new customers acquired. These metrics are useful, but they do not necessarily demonstrate sustained value.
A registered user may never use a service. A merchant may receive a payment terminal but stop using it after experiencing repeated difficulties. A digital platform may attract significant initial interest without becoming an integral part of its users' routines.
To understand whether transformation is working, organizations must look beyond initial adoption.
Relevant measures may include active usage, successful transaction rates, customer retention, service availability, resolution times and reductions in the cost or effort required to complete a task.
For a small business, impact might mean fewer payment-related disruptions, improved transaction records or greater convenience for customers. For a financial institution, it might mean more efficient processes, better service delivery or stronger customer engagement.
These outcomes will differ across sectors, but the principle remains the same: measure what improves because the technology exists, not only what happens when it is introduced.
This requires organizations to establish clear objectives before implementation and to continue evaluating performance after launch. Data should inform decisions about what needs to improve, which features users value and where resources should be directed.
The goal is not to collect more metrics for reporting purposes. It is to use evidence to build better products and deliver better outcomes.
Designing for Africa's Realities
Africa is not a single market with uniform infrastructure, customer behavior or business needs. The conditions that shape digital adoption in one country may differ considerably from those in another. Differences also exist within individual countries, particularly between urban and rural communities.
The ITU's 2025 assessment of digital development in Africa highlighted persistent disparities in internet use, infrastructure and access between urban and rural populations. Such differences reinforce the need to design digital solutions around the environments in which people actually live and work. ITU, State of Digital Development and Trends in the Africa Region .
This means considering affordability, device availability, connectivity constraints, language, digital literacy and the level of support users may require.
It also means recognizing that not every problem needs the most technologically advanced solution. Sometimes, a simpler and more accessible product will deliver greater value than a feature-rich platform that is difficult to use or expensive to maintain.
User-centered design should therefore extend beyond the initial research and development stages. Feedback from customers, merchants, frontline employees and support teams should inform continuous improvement.
The people who use and support digital services often understand practical barriers that may not be apparent during product development. Their experiences are valuable sources of insight, not merely feedback to collect after a problem occurs.
Collaboration Is Essential to Sustainable Progress
The last mile is rarely delivered by one organization alone.
Digital financial services, for example, depend on collaboration among banks, fintech companies, telecommunications providers, regulators, merchants and technology vendors. Each participant contributes capabilities, infrastructure or oversight that influence the quality of the overall experience.
Effective collaboration requires more than signing agreements or connecting systems. It requires clarity on responsibilities, shared expectations, effective communication and a commitment to resolving issues across organizational boundaries.
Interoperability is an important part of this equation because it can help different systems communicate and enable users to transact across services. However, technical connectivity must be accompanied by sound operational processes, appropriate safeguards and clear arrangements for handling exceptions and disputes.
Policymakers also have a role to play in supporting digital infrastructure, consumer protection, responsible innovation and an enabling environment for competition.
Meanwhile, businesses must recognize that digital transformation is not a one-time investment. Products need ongoing maintenance, monitoring, support and improvement if they are to remain useful as customer expectations and market conditions evolve.
Sustainable digital progress depends on treating the ecosystem as a connected whole.
From Digital Adoption to Economic Value
The next phase of Africa's digital transformation should focus on converting access and adoption into sustained economic participation.
For small businesses, this means digital tools that address real operational challenges and support growth. For consumers, it means services that are affordable, dependable and easy to understand. For institutions, it means using technology to improve efficiency, strengthen decision-making and deliver better services.
Achieving these outcomes requires a shift in mindset. Organizations must ask not only what technology they can introduce, but which problems they are trying to solve, whose lives or businesses will improve, and how that improvement will be measured.
This approach also calls for greater investment in the people and processes behind digital products. Technical infrastructure matters, but so do product management, operational expertise, customer support, data literacy and the ability to coordinate complex implementations.
These capabilities help bridge the gap between technological ambition and practical results.
Africa has demonstrated that it can develop and adopt innovative digital solutions. The opportunity now is to ensure that these solutions deliver lasting value across a wider range of communities, businesses and industries.
The Future Will Be Measured by What Works
Africa's digital transformation will not be defined solely by the sophistication of its technology or the speed at which new platforms emerge. It will also be defined by the extent to which these innovations become dependable tools for everyday economic activity.
The questions that matter are straightforward. Can people access the services they need? Can businesses rely on them? Do they reduce friction, improve productivity and create opportunities? And can these benefits be sustained over time?
Answering these questions requires a practical approach to innovation: one that places users at the center, treats operational excellence as a strategic priority, measures meaningful outcomes and encourages collaboration across the digital ecosystem.
The last mile may be where digital ambitions face their greatest challenges, but it is also where their greatest value can be realized.
Africa's digital future will depend not only on the technologies we build, but on how effectively we turn them into solutions that work for people.
AD
Ama Dzigbodi Agbodra
Africa Digital Forum